
 Add as a preferred source on Google
Bitcoin rises despite high rates, seen as portfolio crash insurance
Jeff Park said Bitcoin may provide portfolio crash insurance even as U.S. rates remain elevated. He also sees it underpinning new credit products and tokenized markets built around stablecoins and Treasurys.
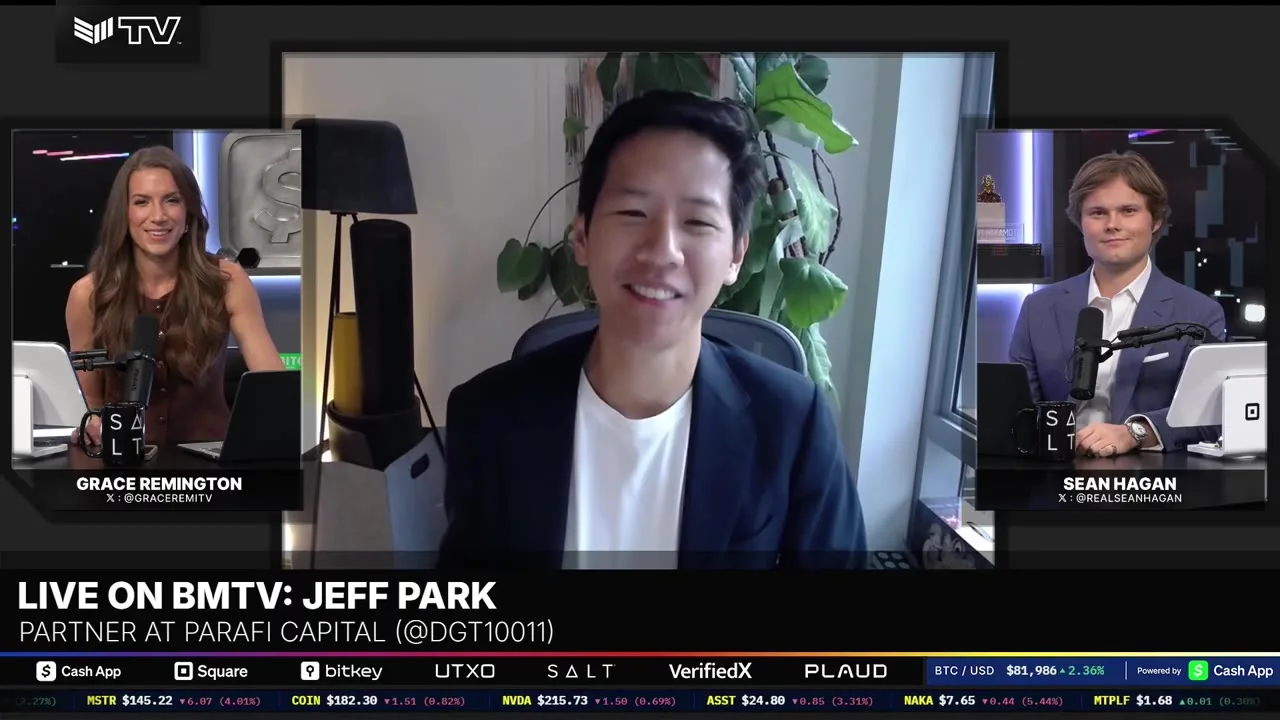
Bitcoin could serve as portfolio crash insurance and as a foundation for new credit and tokenized-finance markets as high interest rates and broader market volatility challenge traditional asset-allocation models.
As volatility spreads across stocks and bonds, investors should distinguish between ordinary diversification and protection against market shocks, according to Jeff Park, partner and portfolio manager at Parify. He argued that Bitcoin’s investment case could remain intact even in a high-rate environment.
In an Oct. 16 Bitcoin Magazine interview, Park said Bitcoin’s demonstrated qualities as a form of money could justify a portfolio allocation. Parify is a New York digital-asset investment firm with almost $2 billion in assets under management.
Citing a Goldman Sachs summer study, Park said single-stock volatility among S&P 500 companies had reached the 99th percentile over the past 15 years, while implied correlations among those stocks were near the zero percentile. The combination points to greater market volatility and wider dispersion between individual securities, creating new investment opportunities.
Uncertainty surrounding interest rates, equities and economic growth is driving risk sentiment, while capital formation and cross-border flows are becoming faster and more technical, Park said. Bitcoin is a significant part of this economic rethink, he added.
Bitcoin also climbed steadily after June even as U.S. 10-year rates rose above 5% and 30-year rates exceeded 5.4%, Park said. That performance challenges the view that Bitcoin benefits only from easy monetary policy and suggests it could also have utility under tighter conditions. He pointed to BlackRock’s advocacy of a 1% to 3% Bitcoin portfolio allocation.
A traditional 60% stock and 40% bond portfolio combines growth assets with the perceived security of a risk-free rate. Park said that framework becomes harder to navigate when the risk-free rate itself is challenged, making it necessary to reconsider the assumptions underlying portfolio allocation.
He also expects further development of credit and income products that use Bitcoin as collateral. Over the next three to five years, investors could gain a wider range of choices across Bitcoin and Bitcoin-adjacent products based on their preferred level of volatility.
Park identified global access to digital dollars and support for dollar dominance as central uses for stablecoins. He cited IMF data showing that nearly 99% of stablecoin usage is dollar-denominated, but said merely shifting funds between existing dollar deposits, money-market funds and cash would not create new demand for U.S. assets. On-chain financial infrastructure could instead connect offshore dollar demand with U.S. capital markets.
Tokenization should first establish the building blocks for stablecoins, tokenized deposits and U.S. Treasurys before expanding to equities and funds, Park said. He described collateral mobility as tokenization’s primary value, citing a Bank of New York transaction with Citadel Securities in which a Treasury settled within minutes and was then used to finance an overnight repo. Such modernization could improve offshore investors’ access to U.S. companies and financial markets.
Riza Dagoc
Riza Dagoc reports on regulation, investing and the digital-asset business for TokenPost. Send corrections or tips to info@tokenpost.com.