
 Add as a preferred source on Google
Yorkville America CEO Sees Gold and Bitcoin as Stages of One Thesis
U.S. debt stood at about $40.4 trillion on Oct. 15, while second-quarter gold net demand reached 289 metric tons.
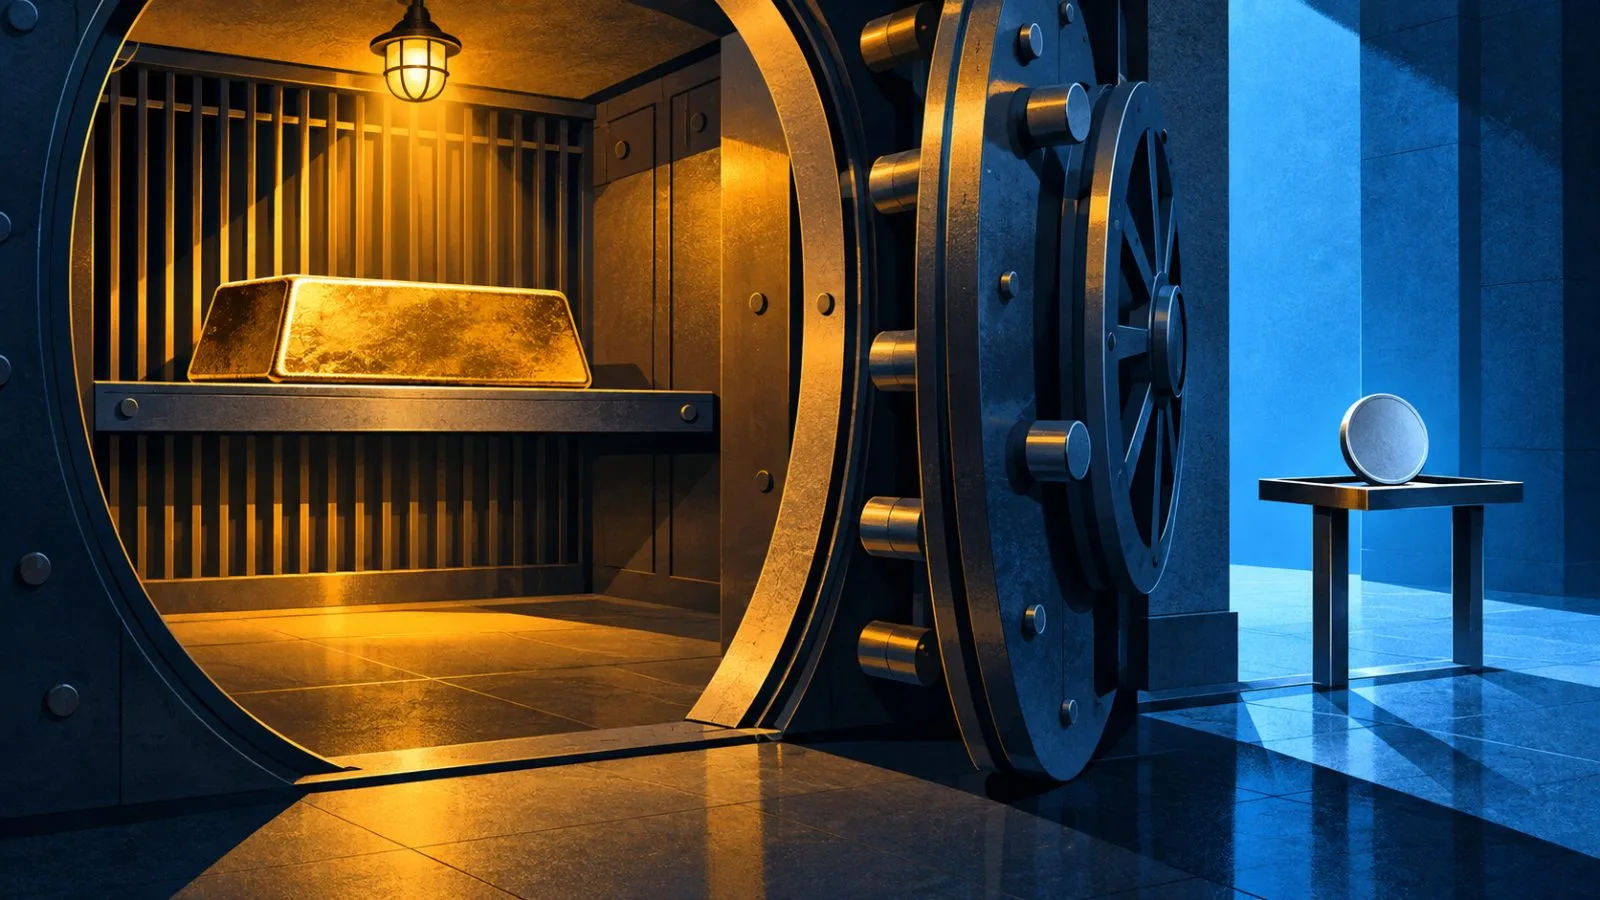
Yorkville America CEO Steve Neamtz sees gold’s place in central-bank reserves and Bitcoin’s route through spot exchange-traded funds (ETFs) as separate institutional stages of one response to fiat purchasing-power erosion.
The distinction, in his view, is not that the assets answer different monetary concerns, but that institutions have different tools for holding them. Gold has long-standing custody and legal frameworks and qualifies for sovereign reserve portfolios. Bitcoin, about 17 years old, has an ETF channel that makes institutional exposure more accessible, yet Neamtz says those products have not given it the reserve standing central banks require. That leaves gold further along in formal adoption even as both assets fit the same debasement thesis.
U.S. figures provide scale for the currency concern behind that thesis. Federal debt stood at about $40.4 trillion on Oct. 15, while preliminary FY 2026 net interest outlays were about $1.14 trillion. The dollar’s purchasing power declined roughly 40% from September 2006 to September 2026. Neamtz links interest in scarce assets to concern that public borrowing and currency expansion can erode what dollar balances buy over time.
Gold’s reserve channel is also visible in official-sector buying. Net demand from central banks and other official institutions reached 289 metric tons in Q2 2026, compared with a revised 57 metric tons in Q1. The figures describe activity in an established reserve market. Bitcoin’s institutional access, by contrast, runs through investment products rather than sovereign reserve programs. For Neamtz, that gap reflects infrastructure and readiness, while both assets fit the same monetary argument.
He distinguishes this thesis from a promise of protection during every market downturn. The case he describes centers on purchasing power over time, rather than a prediction that gold or Bitcoin will rise whenever stocks fall. Neamtz notes that the assets have sharply different volatility profiles, a factor in assessing their relative place in a portfolio. The comparison centers on each asset’s role and institutional access.
Neamtz frames the 2027 portfolio question around how investors might divide exposure between gold and Bitcoin, given their different volatility. Gold’s central-bank infrastructure is established, while spot ETFs have widened Bitcoin access without conferring sovereign reserve status.