
 Add as a preferred source on Google
Debt maturity wall may revive money printing, boosting gold and Bitcoin on weakness
Michael Howell says strong economic growth is squeezing market liquidity, but a looming debt maturity wall could force renewed monetary expansion and support gold and Bitcoin during periods of weakness.

A strong real economy is draining liquidity from financial markets, but mounting debt maturities could eventually force policymakers to expand the money supply again, creating an opening for gold and Bitcoin.
Rapid nominal growth across the global economy is drawing capital into the real economy and tightening financial-market liquidity. As refinancing pressures increase, renewed monetary expansion by major economies could benefit gold and Bitcoin.
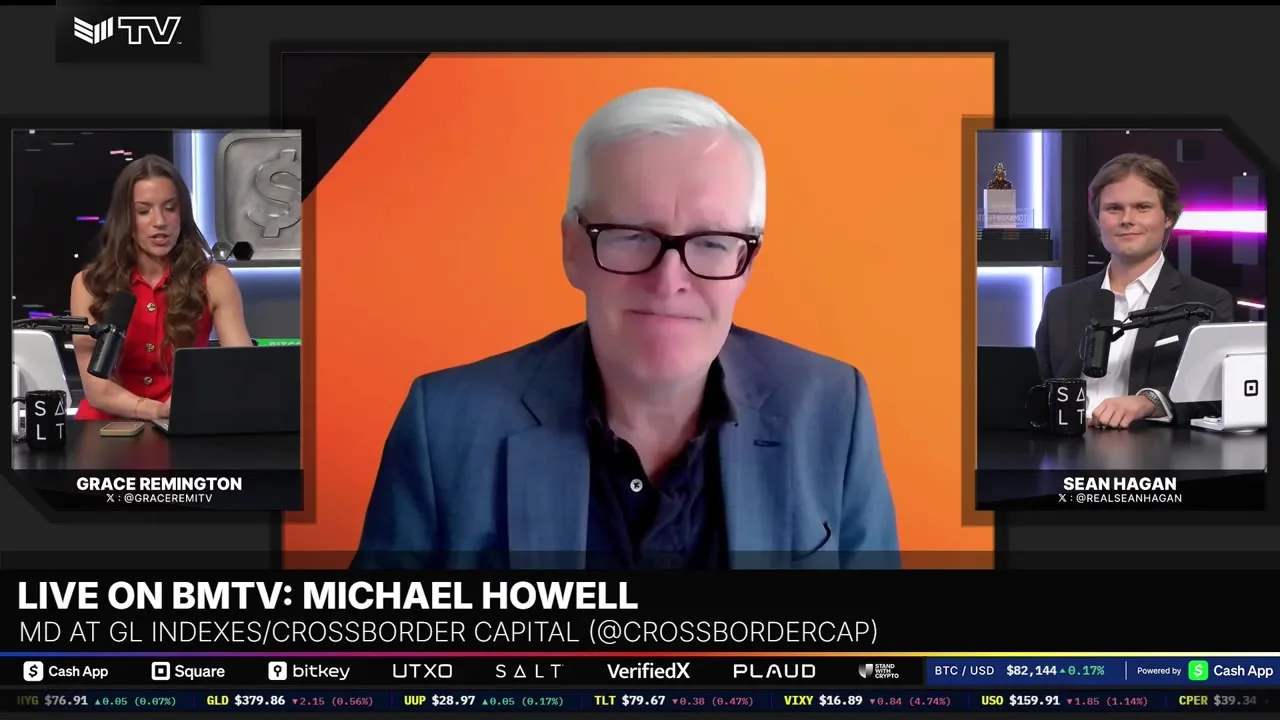
In an Oct. 19 Bitcoin Magazine interview, Michael Howell, CEO of CrossBorder Capital, said the real economy and financial markets are competing for funds, as reflected in rising bond yields and a flattening yield curve.
Howell said nominal growth in the U.S. and worldwide is running at a pace rarely seen since the mid-1980s or early 1990s. While the quality of growth may be weak and inflation is a major component, the real economy is absorbing funds that would otherwise flow into financial markets.
The squeeze is appearing first in less-liquid markets. Howell said the Russell 2000 appeared to be in a bear market and junk-bond spreads had started widening, indicating that liquidity was being pulled from markets. He attributed the shift primarily to a strong real economy crowding out financial assets, rather than aggressive central-bank tightening.
Howell also rejected the view that moves in U.S. Treasuries were chiefly driven by fiscal weakness or political concerns. He said rising U.S. yields largely reflected economic growth, although fiscal fragility could be affecting some European markets, including France.
He interpreted bearish yield-curve flattening as a sign that the liquidity cycle was in its late stages. Higher energy prices, rising yields and a strong U.S. dollar could weaken future growth. Howell said a 3% real yield on U.S. Treasury Inflation-Protected Securities looked attractive, while longer-dated Treasuries were reaching levels worth reconsidering.
The central pressure over the next several years will be a debt maturity wall created when borrowers extended maturities at very low interest rates after COVID. Howell said growing refinancing needs would probably compel policymakers to print money again on a large scale, which would favor monetary-inflation hedges such as gold and Bitcoin.
In the U.S., Howell said debt monetization had shifted from Federal Reserve quantitative easing to a form of Treasury-led QE, with the Treasury issuing short-term bills that banks purchase. He said Treasury bills could reach roughly 30% of total debt outstanding before the current administration ends, extending the trend toward monetization.
Although the liquidity cycle is declining in the short term, Howell expects the downturn to be more benign than the aggressive tightening of 2021-2022. His view was that weakness in gold and Bitcoin should be treated as an opportunity to add exposure rather than abandon the trade.
In China, Howell said low government-bond yields reflected debt deflation and weak growth rather than safety. He expects monetary expansion to become unavoidable, while strict capital controls, large foreign-exchange reserves and compliant state banks could help China defend the yuan’s external value for some time. Its domestic purchasing power could still decline as prices and wages rise, directing hedging demand toward gold.
This article is based on market analysis and does not constitute investment advice regarding any asset.
Riza Dagoc
Riza Dagoc reports on regulation, investing and the digital-asset business for TokenPost. Send corrections or tips to info@tokenpost.com.