
 Add as a preferred source on Google
AI data center slowdown poses stock market risk as midterms test medium-term bullish outlook
Darius Dale says midterm-driven AI restrictions could slow data center construction and force earnings downgrades, while strong profits underpin his medium-term bullish outlook.
A politically driven slowdown in AI data center construction after the US midterm elections could trigger broad cuts in investment risk. Strong corporate earnings continue to support a medium-term bullish outlook, but the coming months could bring greater volatility and declines.
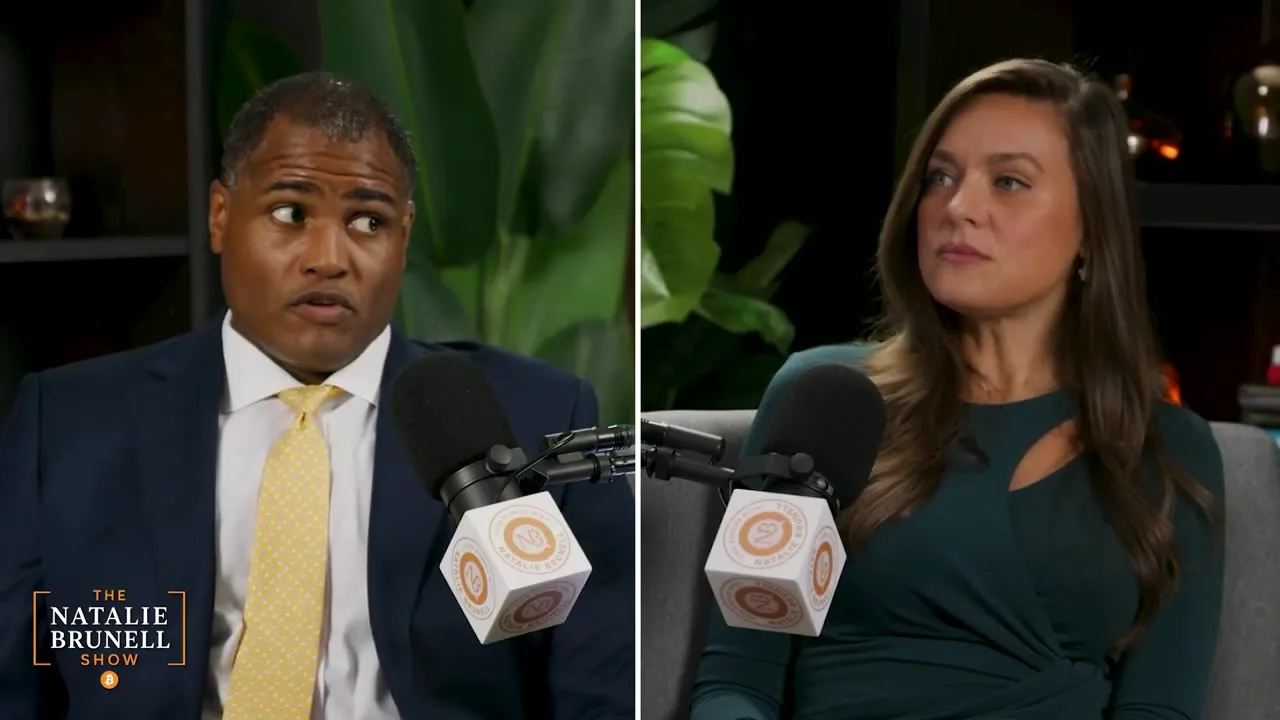
In a November 3 interview with Natalie Brunell, Darius Dale, founder and CEO of 42 Macro, said markets were underestimating the elections’ potential impact on data center investment and earnings expectations. He remained bullish over a three-to-twelve-month horizon but warned that a politically induced construction slowdown could prompt global institutional investors to reduce exposure, much as they did in the fourth quarter of 2018.
Dale said a Democratic takeover of the Senate could signal that opposition to AI among voters was widespread enough to persuade Republican lawmakers facing re-election in 2028 to support federal AI restrictions. Democratic gains at the state level could also constrain construction. However, he put the probability of Democrats winning the Senate below the slightly more than 60% implied by betting markets at the time.
The central risk, he said, was that slower construction would force Wall Street to lower corporate earnings estimates for 2027 and 2028. Dale argued that investor positioning did not adequately account for that shock: markets were treating the political risk as a “speed bump,” while a more substantial obstacle could have serious consequences for asset prices.
Liquidity indicators added to his concerns. Dale said bond term premiums, the US dollar, interest rates and currency volatility had moved in directions that suggested a possible liquidity vacuum. He nevertheless assigned that outcome a probability below 50%, given the strength of the earnings cycle. Investors such as wealth managers were still rotating within equities; a broad contraction in liquidity would be needed to push them out of the stock market, and that had yet to materialize.
Dale attributed recent semiconductor share declines primarily to a shift toward risk aversion rather than deteriorating earnings power. His firm’s systems had identified a risk-off regime earlier in the summer, he said, and investors typically sell shares that are especially sensitive to market swings when reducing exposure. He pointed to demand and order backlogs extending through 2029–2030 discussed in SK Hynix’s earnings release as evidence that the sector’s earnings cycle remained intact.
Weakness beneath the headline indexes could nevertheless foreshadow broader selling, Dale warned. He said 60% of Russell 3000 constituents had fallen 20% from their highs, while his firm’s systems continued to signal a risk-off inflation regime. That did not necessarily imply index-level declines, but he cautioned that the weakness could precede a wider sell-off, as in 2018.
If political developments did not slow data center construction, Dale said strong earnings could support further gains through 2027. He placed the likely peak of the market cycle in the second half of 2027 or the first half of 2028, while expressing doubt that the cycle would last through the 2028 US general election.
Riza Dagoc
Riza Dagoc reports on regulation, investing and the digital-asset business for TokenPost. Send corrections or tips to info@tokenpost.com.