
 Add as a preferred source on Google
Fed’s Bowman Says AI Debt Could Top $800 Billion as Revenue Lags Costs
AI revenue is growing quickly but has not yet covered the costs of models and data centers; potential lease, contract and guarantee payments could exceed the debt by more than three times.
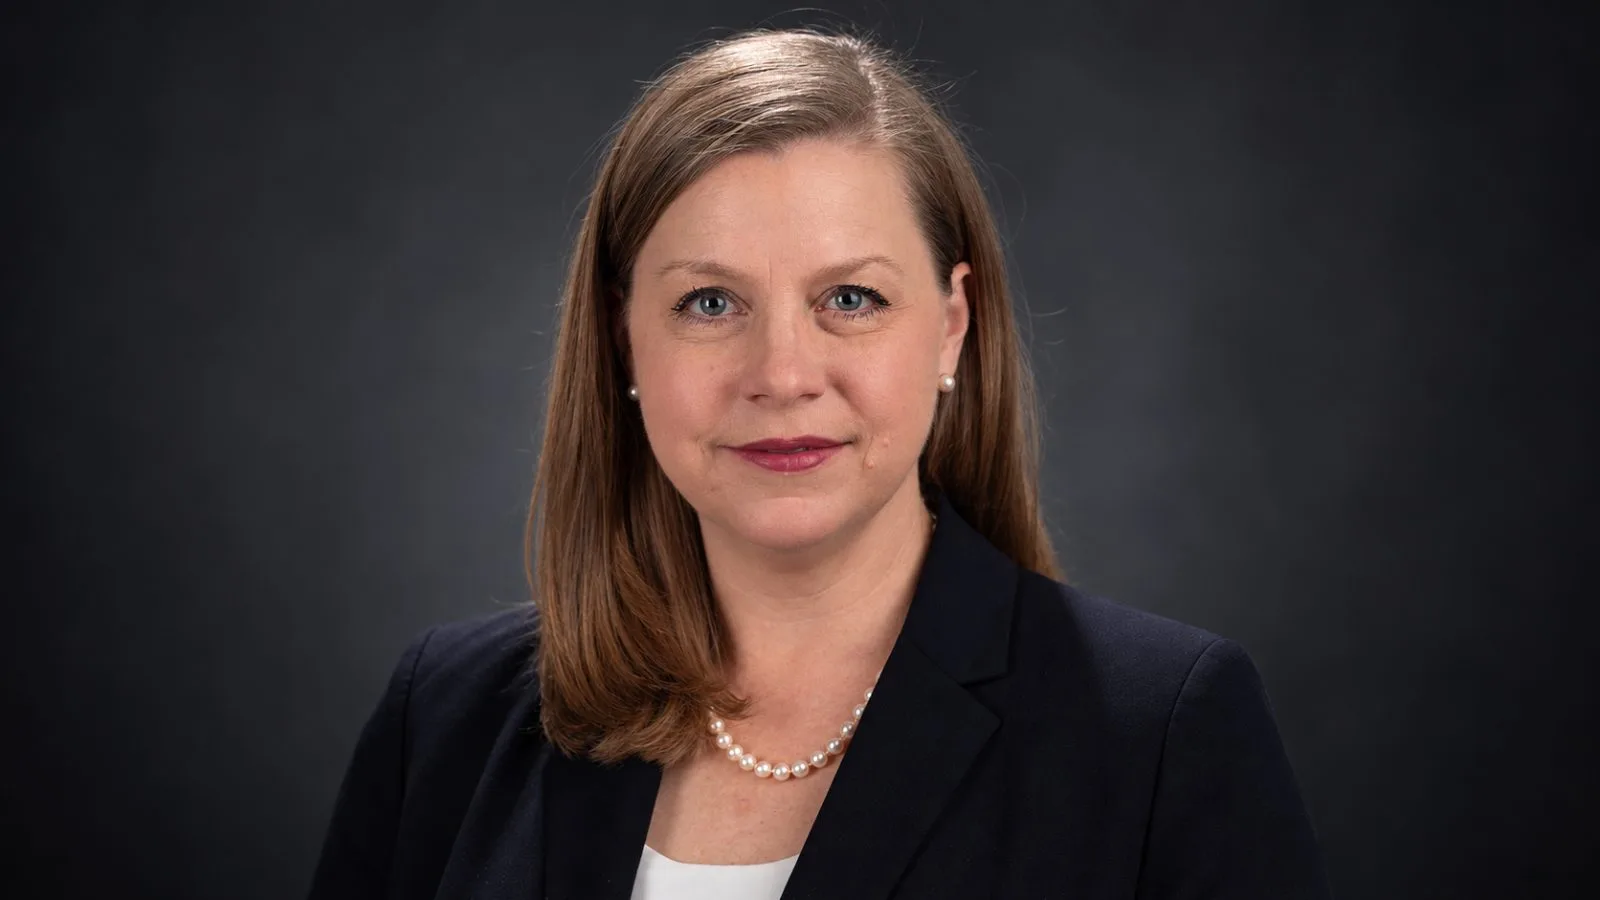
Federal Reserve Vice Chair for Supervision Michelle W. Bowman said AI-related debt could top $800 billion this year, warning that a shortfall against rising costs could trigger share-price declines and tighter credit.
In remarks delivered Nov. 10, Bowman included corporate bonds, private credit and project finance in the estimate. She said potential payments tied to long-term leases, contract commitments and residual-value guarantees could exceed three times the amount of debt.
AI revenue is growing quickly but remains insufficient to cover the costs of maintaining existing models and data centers while developing new ones. As capital spending has surged, hyperscalers and other companies have increasingly turned to credit and equity markets. Real business fixed investment has strengthened to a pace comparable with the 1990s technology boom, with high-tech equipment, software and data center construction accounting for most of its growth since 2025.
Bowman described financing connections between large technology companies, hyperscalers and smaller, riskier firms. Larger companies take on off-balance-sheet obligations that smaller firms use as collateral to finance data centers and computing equipment. Hyperscalers and chip designers also invest in smaller companies that buy their products, creating what Bowman described as the appearance of circular financing.
The largest U.S. bank holding companies have some exposure to AI financing, as do life insurers, pension funds, private-credit firms and mutual funds. Most of these institutions are well capitalized and have stable funding, Bowman said, but complex financing structures can make counterparty risk difficult to assess.
Bowman also pointed to recent declines in technology valuations, wider corporate bond spreads and increases in credit default swaps for some companies involved in the AI buildout. AI financing is also among the risks to the S&P 500 discussed in an earlier report on the index’s downside outlook.
If AI revenue falls short of sharply rising costs, while regulation or local opposition delays projects, company share prices could correct, financing costs could rise and access to credit could narrow. Those pressures could slow AI construction and cool economic activity and inflation.
Bowman said greater clarity on AI-related financing conditions and the sustainability of investment should increase her confidence in future policy decisions.
Riza Dagoc
Riza Dagoc reports on regulation, investing and the digital-asset business for TokenPost. Send corrections or tips to info@tokenpost.com.